How to Correct Accounting Errors and 7 of the Most Common Types
 Postado Por admin in Sem categoria

Content
- What Are the Most Common Errors in Accounting?
- Mixing personal finances with business accounts
- Errors in Bookkeeping
- Common Accounting Errors and Corrections in the AP Workflow
- Transposition and Commission Errors
- Small-Business Grants: Where to Find Free Money
- Finding and eliminating accounting errors
Your business needs financial reporting for compliance and making sure your books are up-to-date. Management reporting is used to make better business decisions backed by data.
How do you classify errors in accounts?
- Errors of Omission: When a transaction is not recorded by mistake in the books of accounts, it is called an error of omission.
- Error of Commission: When a transaction is entered in the books of accounts, it might be entered wrongly.
- Errors of Principle:
- Compensating Errors:
As soon as you spot an error, you should correct it in order to make sure your financial statements are accurate. The information from financial documents like an invoice isn’t entered correctly in the books. Rounding a figure can make your accounting inaccurate and create a series of future errors. Syncing your bank feed in QuickBooks, it’s easy to become complacent and feel the need to eliminate double-checking your bank statements. However, you may find that the bank has made errors of their own that transfer into QuickBooks and create a compounding error effect. Reconciliation errors are errors that occur during the process of making all the accounts or books consistent or congruent. Accounting is the process of recording, summarizing, and reporting financial transactions to oversight agencies, regulators, and the IRS.
What Are the Most Common Errors in Accounting?
For example, the wrong amount is recorded in inventory and is balanced out by the same wrong amount being recorded in accounts payable to pay for that inventory. An error of omission involves no entry being recorded despite a transaction occurring for the period. Accounting errors can include duplicating the same entry, or an account is recorded correctly but to the wrong customer or vendor. Indeed, Friehling’s practice was so small that for years, he operated out of his house; he only moved into an office when Madoff customers wanted to know more about who was auditing his accounts. Ultimately, Friehling admitted to simply rubber-stamping at least 18 years’ worth of Madoff’s filings with the SEC. He agreed to forfeit $3.18 million in accounting fees and withdrawals from his account with Madoff.
- Management reporting is used to make better business decisions backed by data.
- Save receipts and documents of business transactions as proof for your records.
- The error may be the result of an act of omission or commission.
- Accountants deal with the bulk of transactions on a daily basis, so it pays to be rigorous with the data you collect.
- Since this can be challenging for companies with a small staff or where the owner does it all, consider using an outside accountant to review accounts periodically.
- All that is wrong is two of the expense accounts are slightly off.
Jamie Johnson is a Kansas City-based freelance writer who writes about finance and business. Jamie has written about a variety of B2B topics like finance, business funding options and accounting. She also writes about how businesses can grow through effective social media and email marketing strategies. If a small business owner misclassifies an employee, it means federal and state governments miss out on payroll taxes, and the penalties for that could be substantial, according to the U.S. Being late paying your bills isn’t the only ramification of inefficient bill management. Some 82% of U.S. businesses fail because of cash flow problems, according to Visual Capitalist. If you can’t afford a full-time, in-house financial professional, another option is to hire a freelance bookkeeper or accountant who works remotely.
Mixing personal finances with business accounts
These complete omissions do not affect the totals of trial balance. Accounting is the language of business, and accounting errors create miscommunication. If the underlying accounting data is incorrect, the stakeholders who rely on it are more likely to make a misinformed decision. For example, an accounting error can cause a business manager to make a suboptimal operating decision, especially harmful in cases where profit margins are thin or cash flow is tight. Similarly, external lenders might be relying on inaccurate financial statements when making lending decisions. Accounting errors are unintended accidents; they are the result of an inadvertent mistake. Sometimes accounting errors are caused by a slip of the hand, like transposing a number or hitting an incorrect key.
- Similar to Number 6, this error occurs mostly in companies that use bank feeds for data entry purposes.
- Not everybody assumes that running a prosperous restaurant business provides for lots of spare time.
- It’s understandable, especially when a business is just beginning to find its footing.
- In this lesson, we’ll give each of these accounting errors a name.
- It’s better to act preventatively and have a system in place to enter each transaction.
- Here are some common accounting mistakes business owners make, as well as some tips on how to avoid them.
Using one account can make it tougher to sort out your personal and business transactions, which could cause significant issues when tax time comes around. With sloppy financial accounting, you may even miss an expense that you could list as a business deduction. You will have to develop good internal controls and processes to detect errors.
Errors in Bookkeeping
Omitting data affects the balance sheet and can make a company look like it’s doing better than it actually is. It also creates problems when filing your small business taxes. Transposition errors occur when two or more digits that are reversed individually or as part of a larger sequence. It appears as an error in data entry when posting a new recording. Although it is usually small and unintentional, it can result in further miscalculations which can lead to significant financial losses, as well as time invested in order to identify the problem. It involves an employee, account, or corporation itself and is misleading to investors and shareholders.
How are accounting errors corrected?
Often, adding a journal entry (known as a “correcting entry”) will fix an accounting error. The journal entry adjusts the retained earnings (profit minus expenses) for a certain accounting period. Correcting entries are part of the accrual accounting system, which uses double-entry bookkeeping.
Make it a practice to reconcile your bank and credit card accounts every month. Put a note in your calendar to ensure this is done within a few days of receiving your statements. If you’re using bank feeds, reconciliation should only take a few minutes. Reversing accounting entries means that an entry is credited instead of being debited, or vice versa. The issue is that you can’t spot this mistake in your trial balance—it will still be in balance regardless. Cash needs to be increased by $450 and accounts receivable needs to be reduced by $450. The correcting entry journal entry will debit cash by $450 and credit accounts receivable by $450 .
Common Accounting Errors and Corrections in the AP Workflow
For example, if you loan a customer $5,000 but enter only $500 as a loan and $500 withdrawal from your cash account, then you will find that this error is carried to your trial balance. An error of omission occurs when a transaction is completely omitted from the books of your company. You may forget to enter an expense transaction or enter the sale of a product or service. Therefore, you need to make sure you have a solid routine for entering these transactions timely. A strong framework of preventive and detective controls, together with suitable accounting software, can be the most effective way to find accounting errors. This accounting error most frequently happens when a bookkeeper without accounting knowledge is maintaining the books.
- Accounting is the language of business, and accounting errors create miscommunication.
- For example, cash of $400 received from Miss Lily was omitted to record in journal.
- As you can see, he incorrectly switched the 8 and the 1 when recording revenue.
- The best ones can perform complex operations such as data management, creating financial projections, and producing detailed reports.
- If you have information coming in that’s off, being miscategorized, or just all-around wonky, there’s a good chance there’s been a misuse of accounting software.
- The more often you reconcile your accounts, the more likely you are to find accounting errors.
Error of duplication is when an accounting entry is duplicated, meaning it’s debited or credited twice for the same entry. For example, an expense was debited twice for the same amount would be an error of duplication. Similar issues occur when a publicly held asset or non-profit organization undergoes privatization. Top executives often reap tremendous monetary benefits when a government-owned or non-profit entity is sold to private hands. It can also contribute to a public perception that private entities are more efficiently run, thereby reinforcing the political will to sell off public assets.
Transposition and Commission Errors
To avoid misclassifying employees, you must determine if they are employees or contractors based on the jobs they perform, how they are paid and their relationship with your company. No one enjoys piecing together a year’s worth of receipts and documents in April because they were disorganized the other 11 months of the year. That goes double for businesses, which accounting errors must navigate a more complicated route to comply with Uncle Sam’s increasingly complex tax laws. If you’re tackling your business tax filing using the DIY approach, you may stumble if you haven’t taken steps along the way to document your company’s finances properly. Small business owners often blur the line between their personal and business finances.
These errors occur when entries are made against the principles of accounting. Purchase of computer for office use is wrongly entered in the Purchases Day Book. Capital expenditure should not be treated as revenue expenditure.
His involvement makes the Madoff scheme not only the largest Ponzi scheme ever uncovered, but the largest accounting fraud in world history. The $64.8 billion claimed to be in Madoff accounts dwarfed the $11 billion fraud at WorldCom.
- Discover how to identify accounting errors and see different types and their importance.
- In other words, we can say that Suspense Account stands automatically closed when all one sided errors are rectified.
- Following are examples of preventive and detective controls that serve to minimize accounting errors.
- A sale of goods to S.Anish for Rs.1000 is wrongly debited to G.Anish a/c.
When you reconcile your accounts at the end of the month, you validate the information in your books against an external document . Doing this not only helps you detect and address errors, but it also helps you prevent fraud.
Finding and eliminating accounting errors
Compensating errors are those errors which compensates themselves in the net results of the business. A compensating error occurs when two or more errors cancel each other out. For example, if there are over debit in one account then it will be compensated by the over credit in some account in the same extent of the business. It’s not just errors made when entering transaction data into a spreadsheet or failing to note that you paid a bill. Inaccurate financial tracking ultimately costs your business money and undermines your ability to plan for next month or beyond.
Enjoy access to millions of ebooks, audiobooks, magazines, and more from Scribd. Instant access to millions of ebooks, audiobooks, magazines, podcasts and more. It may not be a good idea to assign all financial tasks to a single person. Though it might improve productivity to have only one person handle it, it could also lead to theft or fraud. First call resolution is when customer service agents properly address a customer’s needs the first time they call.
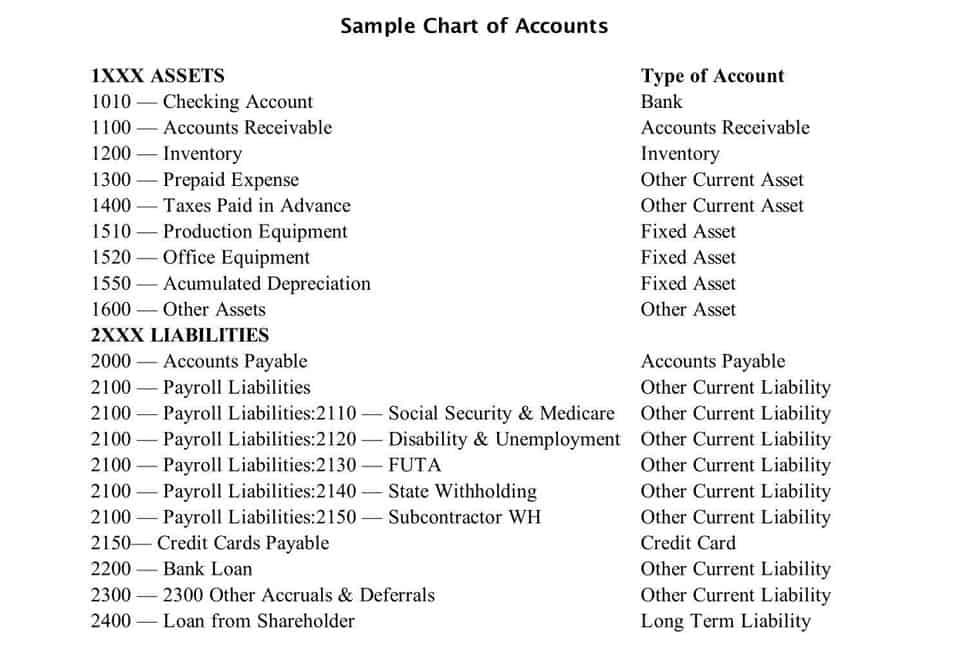
It also ensures you record the interest portion of your loan payments correctly. Too often, the entire loan payment is posted against the principal balance in your books, which means your liabilities and your interest expenses will be understated. Most accounting software allows you to set a closing password on your books at the end of each accounting period. Yet many business owners — and bookkeepers — don’t use this feature.
How to Fix 4 Common Accounting Mistakes
They used this money to pay the top 43 managers of the company. The SEC and the Ontario securities commission eventually settled civil action with Nortel. However, a separate civil action will be taken up against top Nortel executives including former CEO Frank A. Dunn, Douglas C. Beatty, Michael J. Gollogly, and MaryAnne E. Pahapill and Hamilton. These proceedings have been postponed pending criminal proceedings in Canada, which opened in Toronto on January 12, 2012. Crown lawyers at this fraud trial of three former Nortel Networks executives say the men defrauded the shareholders of Nortel of more than $5 million. According to the prosecutor this was accomplished by engineering a financial loss in 2002, and a profit in 2003 thereby triggering Return to Profit bonuses of $70 million for top executives. In fact, in 2015, 33% of all business bankruptcies were caused by employee theft.
Accounting errors are often unavoidable due to the large volume of financial information required to create balance sheets. While it is difficult to prevent errors, a company’s managers can take steps to find mistakes before they have a chance to create long-term problems.
Principle errors
An example of this is designating a type of transaction under the wrong category (e.g., payroll as a fixed-asset purchase). Even if you’re going to require the assistance of an accountant, you should still review your financial statements thoroughly. We also advise against making your bookkeeper the same person who makes your deposits. The best accounting softwares out there offer free training, video demos, and other educational tools not just for the business owner but for his employees too.
The last thing a small business owner wants to go through is a tax audit. But https://www.bookstime.com/ if you do have to, the more paperwork you have, the better off you’ll be.

